Local Corruption Pushes Money Into Housing and Out of Other Sectors
Using a new city-level corruption dataset for China, the authors show that more corrupt cities invest more in residential housing and less elsewhere. Over-investment appears only once corruption passes a threshold, and attractive cities can escape the effect.
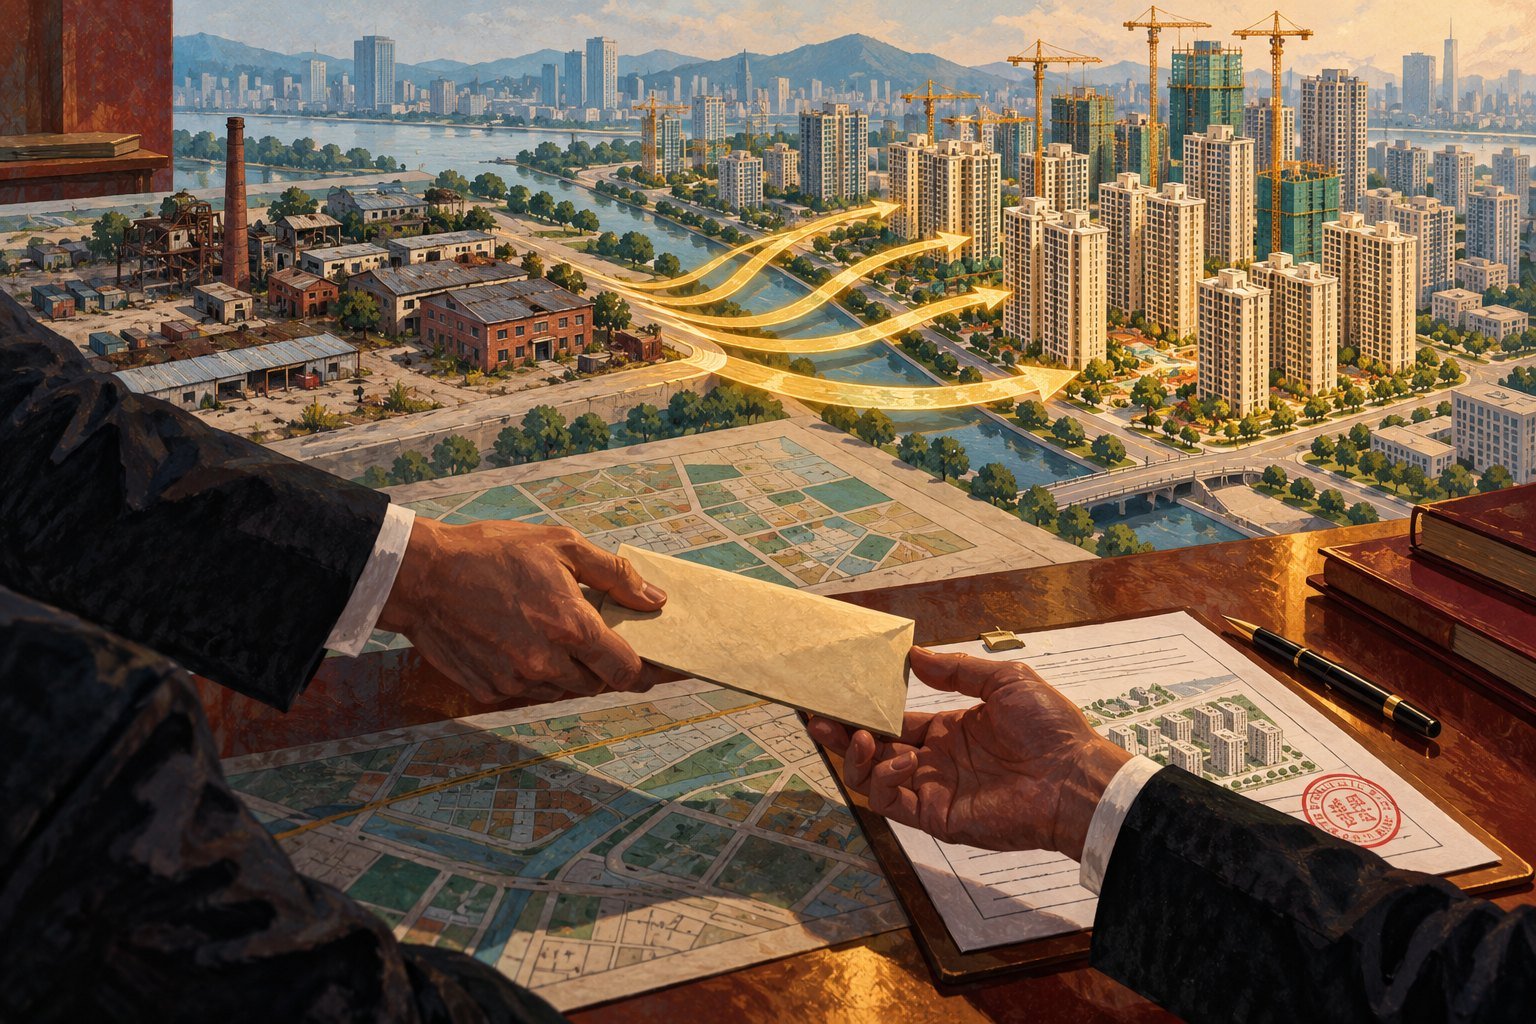
China’s housing boom produced whole districts of empty apartments. A study in the European Journal of Political Economy asks whether local corruption helps explain where that over-building happened. The answer is yes, but only past a certain level of corruption, and not in cities attractive enough to fill the units.
Yao-Yu Chih, Associate Professor of Finance and Economics in the McCoy College of Business at Texas State University, is the lead author. His co-authors are Firat Demir and Hewei Shen of the University of Oklahoma, Chenghao Hu of San Francisco State University, and Junyi Liu of Soka University of America.
The study
The authors start with a stylized model, meaning a simplified economic framework that captures the essential incentives. In it, local officials with discretion over land and permits can extract more from housing projects than from other kinds of investment. That discretion changes where capital flows.
The model produces four predictions. First, higher corruption raises investment in residential housing. Second, higher corruption lowers investment in the non-housing sector. Third, the link between corruption and over-investment is not linear. Over-investment, meaning building beyond what demand supports, appears only when corruption exceeds a threshold. Fourth, city attractiveness can cancel the effect, because a city that draws people and firms can absorb extra housing supply.
To test the predictions, the team built a new dataset measuring corruption at the prefecture city level. China has several hundred prefecture-level cities, so this gives far more variation than provincial data. They then compared corruption scores with housing and non-housing investment across cities.
What the researchers found
The data supported all four predictions. More corrupt cities put more money into residential housing and less into other sectors. The over-investment problem showed up only in cities where corruption was above the threshold. And in cities with strong attractiveness, the corruption effect on over-investment disappeared.
The threshold result matters for interpretation. It suggests that low levels of corruption do not by themselves create ghost districts. The distortion becomes visible when corruption is high enough to dominate the investment decision.
What it means for investors and policymakers
For real estate investors, the study offers a way to read risk in emerging markets. Housing investment that runs ahead of demand in a city with weak governance may reflect rent-seeking rather than fundamentals. City attractiveness, measured by the ability to draw residents and businesses, is the counterweight to watch.
For policymakers, the results connect anti-corruption efforts to capital allocation. Reducing corruption in the cities above the threshold should shift investment back toward productive non-housing uses and reduce the stock of unsold housing. Efforts aimed at cities below the threshold may yield less change in the housing market.
For researchers, the paper demonstrates the value of measuring corruption at a fine geographic scale. Many of the effects would be hidden in provincial averages.
The findings come from China, whose land system gives local governments unusual control over housing supply. Whether the same mechanism operates where land is privately owned is a question for future work.
This summary is based on the paper’s abstract. The full article reports the data, methods, and detailed results.
What it means for managers
- Corruption tilts capital toward housing. Cities with higher local corruption invested more in residential housing and less in non-housing sectors, consistent with the model's predictions.
- There is a tipping point. Corruption correlated with housing over-investment only after it exceeded a threshold, so modest corruption did not produce the same distortion.
- City appeal offsets the damage. In attractive cities, demand can absorb the extra housing, so the corruption effect on over-investment can be neutralized.
Chih, Y.-Y., Demir, F., Hu, C., Liu, J., & Shen, H. (2026). Residential housing investment and local corruption: Empirical evidence from the Chinese housing market. European Journal of Political Economy, 93, 102850. 10.1016/j.ejpoleco.2026.102850
Related
How Hotels and Restaurants Adopt Immersive Technology to Co-Create Guest Experiences
A forthcoming exploratory study looks at how hospitality firms take up immersive technologies such as virtual and augmented reality, and how guests and firms create value together in blended physical and digital settings.
Taewon Suh
What Happens When Ads Say They Were Made With AI
A new study led by a McCoy College marketing professor tests how disclosing that an ad was generated by AI affects consumer attitudes, purchase intent, and social media engagement. The abstract was not available when this summary was written, so results are not reported here.
Rick Wilson
CEOs Facing Large Capital Gains Taxes Pledge More Shares as Loan Collateral
Executives sitting on big unrealized gains borrow against their stock instead of selling it, and the bigger the tax bill they would face, the more they pledge. Boards seem to know this: firms with high-tax-burden CEOs resisted antipledging rules and paid more when they adopted them.
Jon Underwood